Table des matières
Recording WEEE
In France, WEEE or D3E (Waste Electrical and Electronic Equipment) is a tax on all electrical and electronic equipment, applicable in France.
Gestan enables the management of WEEE, which must be declared on each product sheet.
Enabling the feature
This feature is enabled by ticking the box WEEE Management on the general settings screen.
Recording WEEE
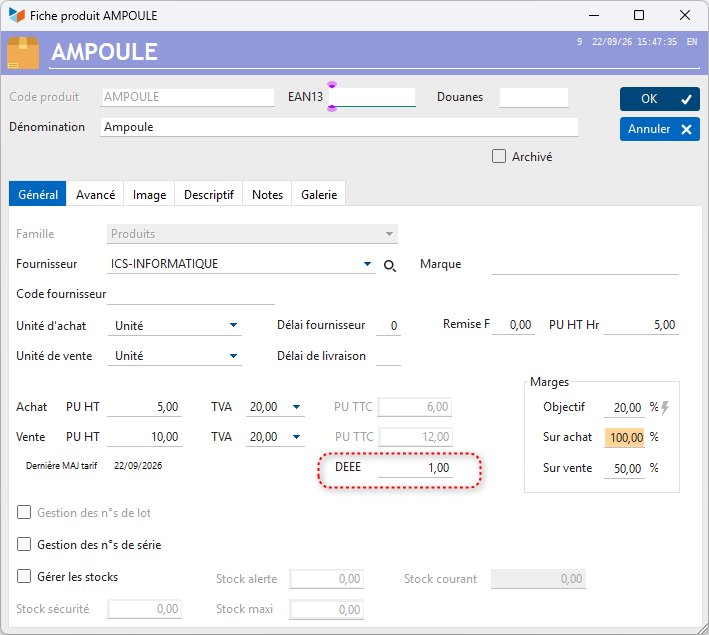
When the WEEE management feature is enabled, a field on the product details page allows you to enter the amount of this tax for each relevant product.
Accounting for the WEEE tax
The WEEE tax is a taxable item, as it forms part of the VAT calculation, and this principle does not appear to cause any concern amongst tax specialists.
For example, for a computer sold, we have:
Article : écran

Prix catalogue             300,00 €
Remise client               -15,00 €
────────────────────────────────────
Prix net HT                285,00 €

DEEE                           2,50 €
TVA 20 %                      57,50 €
────────────────────────────────────
TTC                          345,00 €
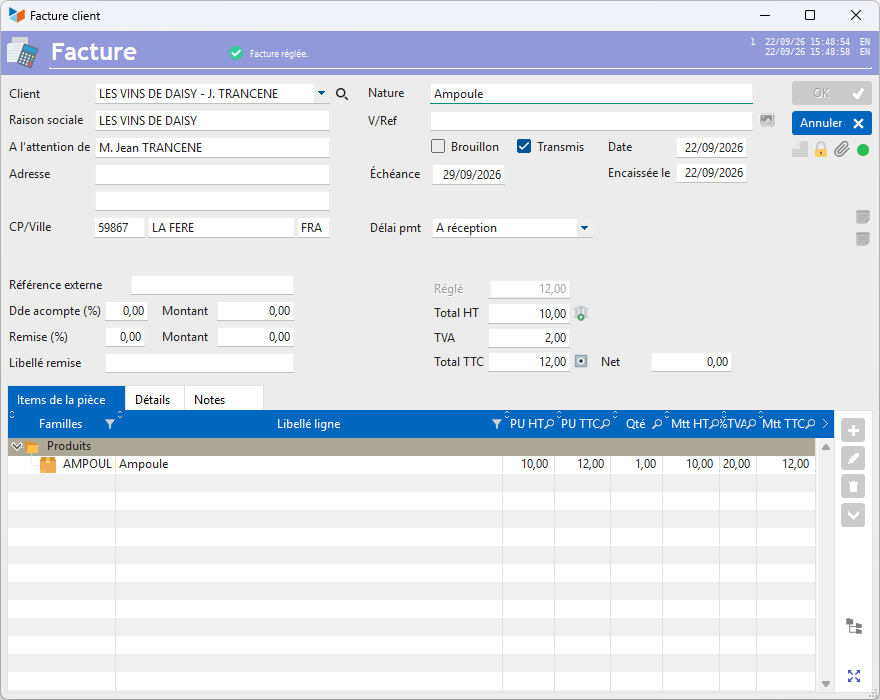
Let’s take the example of an invoice for this light bulb. Its price is 9 euros, plus 1 euro in WEEE tax.
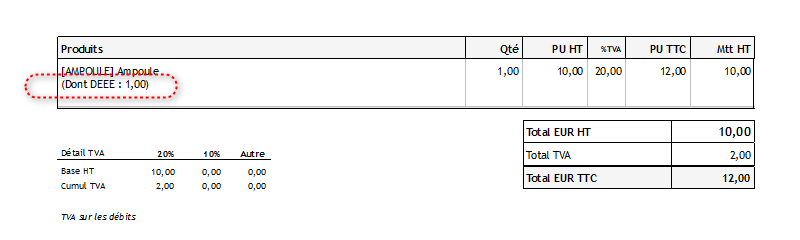
This is what will be printed on the invoice:
And here are the journal entries that will be generated once payment has been made:
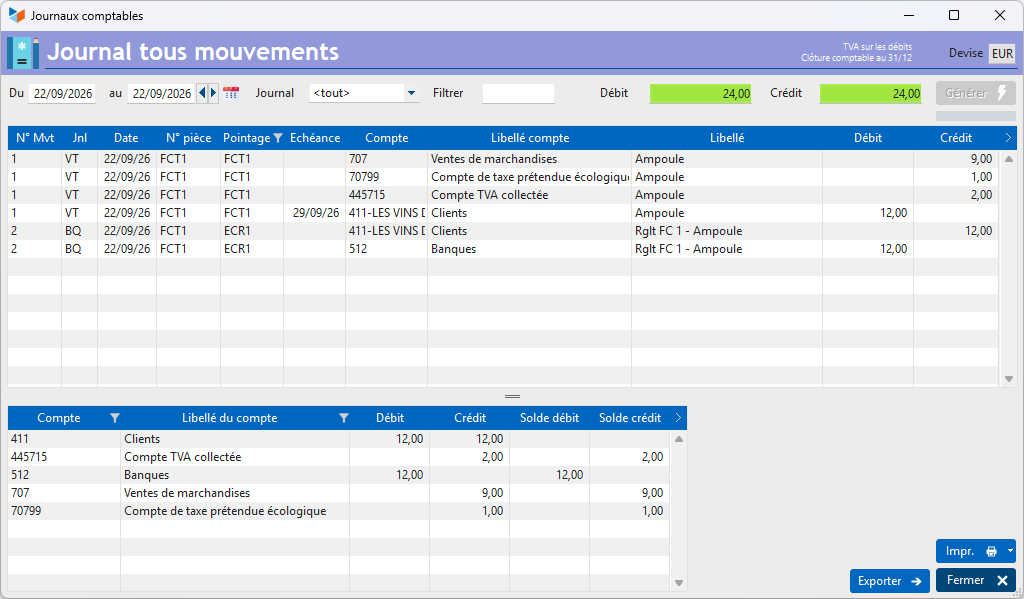
The account to which the WEEE charge is posted is configured in the accounting settings screen.
 The DEEE tax is a little marvel of fiscal and administrative ingenuity: it manages to waste everyone’s time – manufacturers, retailers, accountants, and… ERP software providers – in proportions inversely proportional to the revenue generated by this tax.
We eagerly await, in the same vein, the regulatory provision that will reduce VAT from 20 per cent to 10 per cent on any purchase of a pair of shoes by people with one leg, under the pretext of tax equality and disability inclusion.
This very French brand of fiscal creativity – failing to create wealth, we create constraints – is no doubt linked to the loss of competitiveness it inflicts, much to the delight of other countries: it would have been far simpler to add a turnover tax to the taxes levied on the manufacturers producing these devices, and to increase taxpayers’ tax burden across the board without needing to invent a new tax on top of the many that already exist. Above a certain threshold, having an encyclopaedic knowledge of lepidoptera is no longer profitable, and becomes counterproductive.
ℹ️ Other ‘Accounting’ articles
Arrêtés de TVA
Balance
Balance tiers
Calcul de la TVA
Certification des logiciels de caisse
Clôture comptable / Exercices comptables
Comptabilisation des DEEE
Comptabilisation des écritures
Comptabilité avec Gestan : principes de base
Comptabilité en partie double
Compte bancaire et de caisse
Compte de résultat
Créances irrécouvrables
Encaissements/Décaissements
Export CFONB
Export SEPA
Export XIMPORT des données comptables
Facturation par taux de taxe
Grand Livre
Immobilisations
Imputations comptables
Journal
Journaux comptables (codes)
Lettrage
Liaisons comptables
Liaisons en masse : écritures
Micro-Entreprise / Auto-Entreprise
OD (opérations diverses)
Options des documents comptables
Paramétrage comptabilité
Pièces sans imputation
Plan comptable
Pointage TVA
Produits et Charges
Rapprochement bancaire
Relevés de compte bancaire
Remise de chèques
Revue des écritures
Soldes de gestion
Taux de TVA
Ticket Z
Trésorerie prévisionnelle *
Trésorerie simplifiée
Ventilation des factures par échéances
Ventilation des écritures
Ventilation détaillée par taux de taxe